Chapter 3 - The Ghost on My Credit Score
The paper felt strangely heavy in my hands, like lead sheet rather than twenty-pound copy stock.
I stared at the numbers. *14,210.88.*
The date: October 14, 2022.
I remembered that week with horrifying clarity. It was the week Tate had called me three times in two days, claiming he was finally getting big commercial drywall subcontracts from a developer in Huntersville. He had come over to our house for Sunday dinner, bringing a cheap box of pastries from the grocery store. He had hugged Laurel; he had tossed Beckett into the air until my son squealed with delight.
And while he was sitting at our dining table, drinking my beer, he had already possessed my Social Security number, my date of birth, and my pristine credit rating.
"How?" My voice sounded hollow, like it was coming from the bottom of an empty well. "Wes, how did he do this? You can't just walk into a bank and say 'I'm Oliver Miller' without ID."
Wes dragged a chair over from the side wall and sat directly opposite me, leaning his forearms onto his knees.
"Online commercial application, Olly," Wes said grimly. "Back in late 2022, Truist was aggressively pushing unsecured small-business credit lines to compete with Chase and Amex. You didn't have to walk into a branch. You uploaded a driver’s license scan, typed in a Social, gave an EIN or set it up as a sole proprietorship, and linked a bank account. What documents does Tate have access to? Does he have copies of anything of yours?"
My mind raced backward through the years, tearing through filing cabinets and shared family history.
"When Dad had his prostate surgery four years ago," I stammered, the realization hitting me like a physical blow to the sternum. "Mom panicked. She demanded that both Tate and I be listed on Dad’s medical power of attorney and their secondary family trust account just in case something went wrong on the table. We all went down to the credit union together. We had to provide full copies of our driver's licenses, Social Security cards, and utility bills for the notary file. Mom kept a complete manila folder with copies of all of it in her unlocked desk drawer in the den."
Wes closed his eyes and let out a long, slow breath through his nose. "And Tate has been in and out of that house three times a week for his entire adult life."
"He stole my identity," I said. Saying the words out loud made my chest seize. "My own brother stole my identity to fund his business."
"Worse than that," Wes said, leaning forward and tapping the paper again. "Look at the payment history on this line. See those monthly minimum payments? Two hundred dollars here, three hundred there. For eighteen months, he kept it just current enough that it didn't trigger a credit monitoring alert. Small business lines of credit often don't report to personal credit bureaus unless they go thirty days delinquent. As long as he was making the minimum juice payment, it stayed invisible to Experian."
"Until last month," I said.
"Until last month," Wes confirmed. "When he ran out of cash completely. He missed the March payment. The thirty-day grace period expired last Tuesday. Truist flipped the switch, reported the default to the personal credit bureaus under the guarantor's Social Security number, and boom—there it is. Right on your profile."
I leaned back in the chair, staring up at the white drop ceiling of Wes's office.
Fourteen thousand dollars in personal bailouts over four years.
Eighteen thousand dollars remaining on an auto loan that was sixty days delinquent.
Fourteen thousand two hundred dollars on a fraudulent commercial line of credit.
Tate hadn't just taken a couple hundred bucks here and there for groceries. He had built an entire financial scaffold of fraud and debt, anchored entirely into my back, and the weight of it was about to snap my spine.
"What is the legal definition of this?" I asked quietly.
Wes’s expression turned utterly cold. "It's bank fraud, Oliver. It's identity theft. It's wire fraud if he submitted the application electronically across state lines. Under North Carolina General Statutes and federal law, taking out an unsecured credit line over ten thousand dollars using another person’s identifying information is a Class G felony. If you walk into the Mecklenburg County Sheriff’s Department or the Gastonia Police with these documents, Tate isn't looking at a stern lecture from your mother. He’s looking at handcuffs, an arraignment, and state prison time."
The word *prison* hung in the cold, conditioned air of the office.
My brother. The boy I had shared a bunk bed with. The boy who had taught me how to throw a curveball behind the middle school. The man who had sat at my son’s birthday party forty-eight hours ago, smiling while his wife carried out a neon-pink cake to erase my boy from his own day.
"I need to call Laurel," I said.
"No," Wes said firmly, putting his hand on my shoulder. "You do not call Laurel from this parking lot while you're hyperventilating. And you sure as hell do not call your mother, and you do *not* call Tate."
"I have to confront him, Wes! He stole fourteen grand in my name!"
"And what will happen the second you confront him?" Wes demanded, his voice sharp as a scalpel. "He’ll call your mother. Your mother will call you crying, having a fake panic attack, screaming that you're going to destroy the family. Your father will tell you to 'keep the peace.' Tate will lie, destroy his computer, shred whatever papers he has at the Sycamore house, and try to claim you authorized the credit line to help him start his business. It’ll become your word against his in a messy family dispute, and the bank won't care who's crying—they’ll just sue you for the money because you're the one with assets."
Wes stood up, walked around his desk, and pulled a business card from a small silver holder. He slammed it down on top of the credit report.
"Marcus Vance," Wes said. "My cousin. He was an assistant district attorney in Mecklenburg for eight years before he went into private practice specializing in financial litigation and white-collar defense. He knows every prosecutor and judge in this district. You are going to take these files, you are going to drive four blocks to his office, and you are going to let a lawyer build this wall before you swing a hammer. Do you understand me, Olly? You do not say a single word to your family until Marcus gives you the green light."
I looked at the card. *Marcus Vance, Attorney at Law.*
"Okay," I whispered. "Okay."
***
Forty-five minutes later, I was sitting in a high-rise office on South Tryon Street in downtown Charlotte.
Marcus Vance looked like an older, more cynical version of Wes. He had sharp gray hair, an expensive charcoal suit, and the completely detached, predatory calm of a man who spent forty hours a week watching people lie under oath.
He listened to me for twenty minutes without interrupting. He took notes on a yellow legal pad identical to the one sitting in my kitchen. He examined the auto loan documents, the Truist credit report, and the itemized list of cash transfers I had compiled with Laurel.
When I finished, Marcus set his gold fountain pen down on the mahogany desk with a quiet *click.*
"This isn't complicated legally, Oliver," Marcus said, his voice deep and measured. "It's emotionally horrific, but legally, it's very simple. You have two distinct paths forward, and you need to decide right now which one you're willing to walk."
"Tell me," I said.
"Path one," Marcus said, holding up a single finger. "You treat this as family. You sit down with your brother and your parents. You tell them what he did. You demand that he refinance the truck into his own name or sell it immediately, and you demand that your parents take out a home equity loan or empty their retirement to pay off the fourteen thousand dollars at Truist. In exchange, you don't call the police. You keep the family intact, your mother doesn't have a stroke, and you eat Thanksgiving dinner across from a man who committed a felony against you."
"And if he refuses? If my parents don't have the money?"
"Then you're stuck holding the bag," Marcus said plainly. "Because the second Truist realizes you knew about the fraud and tried to negotiate an informal private settlement without reporting it, you lose your status as an innocent victim of identity theft. You compromise your ability to file a fraudulent dispute with the credit bureaus."
Marcus held up a second finger.
"Path two," he continued. "We treat this as what it actually is: grand larceny and bank fraud. This afternoon, I draft a formal Identity Theft Affidavit under the Fair Credit Reporting Act. You sign it under penalty of perjury. We file a comprehensive criminal complaint with the Charlotte-Mecklenburg Police Department and the Gastonia Police Department. We send certified legal notices to Truist and Piedmont Federal, attaching the police report, demanding the immediate freezing of the accounts and the total removal of all negative marks from your credit profile."
"What happens to Tate on Path Two?"
Marcus looked me straight in the eye without blinking. "The bank's corporate fraud division will take the file. They don't have family dinners, Oliver. They have insurance policies and legal departments. They will refer the case to the district attorney. Within sixty to ninety days, a detective will knock on Tate’s front door with a felony arrest warrant. Depending on his criminal history and the prosecutor's mood, he’ll be facing twenty-four to thirty-six months in prison, plus mandatory restitution."
I felt the blood drain from my face.
My brother in handcuffs. Emma watching her father being put into the back of a patrol car. My mother collapsing on her living room rug, screaming that I had destroyed her family.
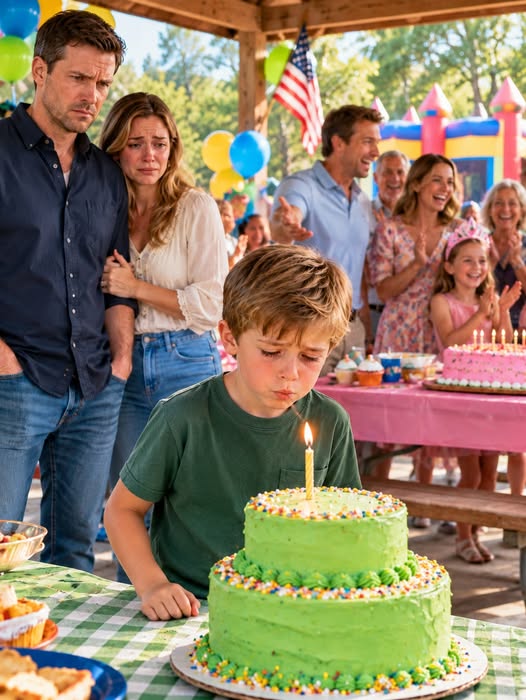
*Beckett blew out his candle alone.*
The memory hit me with the force of an electric shock.
Beckett sitting on that picnic bench. Picking the frosting off his cupcake with his thumbnail. Asking if Emma’s birthday mattered more than his.
Tate hadn't thought about Emma when he committed bank fraud; he had used her as a human shield. He had used her at the park to steal Beckett's birthday, and he was using her now to keep me from defending my own children's future.
"Marcus," I said, my voice steadying. "Is there a third path?"
Marcus leaned back, a faint, razor-thin smile touching the corner of his mouth.
"There is," the lawyer said. "It's called leverage. We prepare Path Two completely. We draft the affidavits. We prepare the police reports. We pull the IP addresses, the bank records, and the signature cards from Truist. We have the gun fully loaded, the safety off, and the paperwork sitting in a sealed envelope. Then, we let your family have the meeting they so desperately want."
"What meeting?"
As if on cue, my phone buzzed on the mahogany desk.
It was a text from my father. Richard Miller rarely texted. When he did, it was usually three words long.
This text was different.
**Dad:** *Oliver. Your mother is inconsolable. Tate and Jolene came over to the house this morning in tears. Tate says you’ve been ignoring his messages and threatening to pull his truck. We are having a family meeting this Sunday at two o’clock at our house. Laurel and the kids need to come. We are going to settle this like a family once and for all. Do not be late.*
I looked up from the screen to Marcus.
"Sunday at two," I said. "My parents' house."
Marcus smiled. It was not a kind smile.
May you like
"Perfect," Marcus Vance said, reaching for his fountain pen. "That gives me five days to pull every bank record, every application IP log, and every canceled check from Truist and Piedmont Federal. You go home, Oliver. You kiss your wife, you play with your son, and you let me do my job. On Sunday afternoon, you won't be walking into an ambush. You’ll be walking into an execution."
***