Chapter 2 - The Ledger of Silence
By seven o’clock that evening, the yellow legal pad was half full.
The kitchen table looked like a war room after a catastrophic retreat. My laptop was open to our bank’s online portal, the blue screen casting a sterile, fluorescent glow over stacks of printed PDF statements dating back four years. Beside the computer sat a mug of reheated black coffee that had gone cold twice, an empty stapler, and our shared family calendar from the past three years.
Laurel sat to my left, her reading glasses perched on the bridge of her nose, her finger running down the digital columns of our joint checking account.
"October twelfth of last year," she said, her voice entirely devoid of warmth. "A debit of four hundred and eighteen dollars to Piedmont Federal Auto Finance. What was that?"
I winced, looking down at the legal pad. "That was the month Tate’s client in Huntersville supposedly contested the invoice for the drywall work. Tate called me from the auto parts store, claiming Piedmont Federal was sending a tow truck to his house the next morning if the balance wasn't settled. He said Jolene was crying in the kitchen."
"Did you pay it directly to Piedmont?"
"Yeah. Over the phone with their automated system."
"Write it down," Laurel said, her pencil tapping the edge of the table. "Line fourteen."
I wrote: *10/12 - Auto loan arrears: $418.00.*
"November eighth," Laurel continued, scrolling down the screen. "Another four hundred and eighteen."
"He told me his knee went out," I muttered, staring at the black ink. "He said he had to buy a knee brace and pay for an urgent care visit."
"Write it down."
*11/08 - Auto loan arrears: $418.00.*
"December third," she said. "Four hundred and eighteen. Plus a late fee of thirty-five."
I didn't even offer an excuse for that one. I just wrote it. By the time we reached April of the current year, I had covered eleven out of the last eighteen monthly payments on Tate’s Ford F-150. That was $4,598.00 just to keep the finance company from dispatching a repossession agent to his driveway—a repossession that would have instantly eviscerated my credit score, which Laurel and I had spent seven years cultivating to secure a low-interest mortgage on our home.
Tate had known that. He had banked on it. He knew that as a co-signer, my financial neck was in the exact same noose as his, but unlike him, I actually cared about strangulation.
"Keep going," Laurel said, her voice dropping into a register that was eerily calm. "Let's talk about the house on Sycamore Street."
"Laurel, that was three years ago—"
"I don't give a damn if it was three centuries ago, Oliver. Put it on the paper."
I swallowed the dry lump in my throat and flipped back through the older statements. In the summer of 2021, Tate and Jolene were being evicted from a dilapidated rental duplex after falling three months behind on rent. The landlord had already filed the summary ejectment paperwork at the Gaston County courthouse. Mom had called me at my office on a Tuesday afternoon, sobbing so hard she could barely articulate the words, claiming that little Emma—who was barely three at the time—was going to be thrown out onto the street with her toys in black trash bags.
I had driven down to the property manager's brick office in Gastonia during my lunch break. I wrote a personal check for two thousand four hundred dollars to cover the security deposit and first month's rent on a small three-bedroom ranch on Sycamore Street.
Tate had promised to pay me back in sixty days. *Just until my tax refund hits, bro.*
The refund came and went. In August of that year, Tate bought a brand-new fifty-five-inch flat-screen television and an electric smoker from Lowe's, which he proudly displayed on his back patio during Labor Day weekend. When I brought up the two thousand four hundred dollars while we were standing by the grill, he had laughed, clapped me on the shoulder, and said, "Man, you’re doing so good at that logistics firm, why are you sweating your big brother over chump change? We’re family, Olly. Don't be so corporate."
I wrote on the legal pad: *June 2021 — Sycamore St. rental deposit & first month: $2,400.00.*
Then came the smaller things. The paper cuts that bleed a man dry over a decade.
* March 2022: Replacing the commercial paint sprayer he borrowed from my garage and returned with a cracked casing and dried latex clogging the piston: $480.00.
* July 2022: Two new tires for his truck because he ran over a box of drywall screws at a job site and didn't have road-hazard coverage: $360.00.
* December 2022: Christmas gifts for Emma and Jolene that Laurel and I bought because Tate claimed they had zero dollars for presents, only for him to show up to Christmas dinner wearing a brand-new Carhartt winter jacket and boots: $450.00.
* September 2023: Emergency plumbing repair at his rental house when a pipe burst and the landlord refused to fix it immediately: $620.00.
I added up the columns using the calculator on my phone.
The digital screen displayed the final sum: **$13,846.00.**
Nearly fourteen thousand dollars.
Fourteen thousand dollars pulled out of our savings, our vacation funds, our home maintenance reserve, and Beckett’s college 529 account. Fourteen thousand dollars spent insulating a grown man from the basic, boring consequences of being an adult.
Laurel looked at the number. She didn't yell. She didn't throw her hands in the air. She simply stood up from the table, took her coffee mug to the sink, rinsed it with cold water, and placed it upside down on the drying mat.
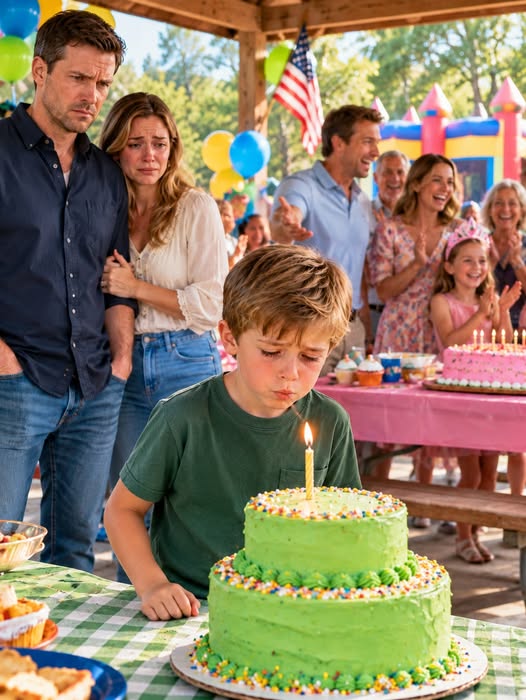
"Fourteen thousand dollars," she said, her back to me. "And today, he couldn't even let your son have a single slice of dinosaur cake."
She walked out of the kitchen. A moment later, I heard the soft click of our daughter's bedroom door upstairs as Laurel went to read Margot a bedtime story.
I was left alone in the kitchen with the hum of the refrigerator and the yellow legal pad.
My phone, resting face-up beside the mousepad, buzzed with an incoming text. Then another. Then three more in rapid succession.
The family group chat was still raging.
I picked it up.
**Aunt Connie:** *I just don't understand why Oliver had to make such a public statement. If he had an issue with Emma having a cake, he could have pulled Tate aside privately. Walking out like that in front of his in-laws and school friends made the whole family look dysfunctional.*
**Uncle Keith:** *Agreed. Kids don't notice that stuff anyway. Emma was thrilled. That's what matters. Beckett had a bounce house for Pete's sake.*
**Tate:** *Look guys, I don't want anyone taking sides. Olly’s always been high-strung. He’s got that corporate pressure, you know? He probably just had a bad week at the office and snapped. I forgive him. Whenever he's ready to apologize to Jolene for making her feel like an intruder, my door is open. We’re brothers. I love him.*
**Mom:** *Thank you, Tate. That is very mature of you. Oliver, did you see what your brother wrote? He is willing to move past this. Please text him.*
I stared at Tate’s message.
*I forgive him.*
The absolute, breathtaking gall of it. He had hijacked my son's party, publicly humiliated my six-year-old child, humiliated my wife, used my money to pay for the truck he drove to the park, and now he was offering me absolution from his self-constructed moral high ground.
I didn't type a reply. I didn't leave the group chat. I simply muted the notifications for eight hours, set the phone down on the table, and walked out to the garage.
The garage smelled of motor oil, lawn fertilizer, and cedar sawdust. In the far corner, tucked beneath my workbench, sat a heavy plastic storage bin labeled *TAXES & LOANS — 2020-PRESENT.*
I pulled the bin out, popped the red plastic latches, and began digging through the thick manila folders until I found the original paperwork from Piedmont Federal Credit Union for the 2017 Ford F-150.
I unfolded the thick legal document under the fluorescent shop light.
There it was. My signature on the line marked *CO-BORROWER / GUARANTOR.* Tate’s messy, looping scrawl was right above mine under *PRIMARY BORROWER.*
I pulled out my phone and logged into the Piedmont Federal mobile app using the login credentials I had created six months ago just to monitor the account.
My stomach plummeted.
There, glowing in red font on the screen, was a notification I hadn't seen:
**STATUS: 62 DAYS PAST DUE.**
**CURRENT BALANCE: $18,420.15**
**NEXT ACTION: REPOSSESSION WARNING ISSUED APRIL 14.**
Two months.
I had paid the February payment. But Tate had completely skipped March, and he hadn't touched April. Because I had been busy with Beckett's birthday preparations and a massive logistics contract at work, I hadn't checked the app in six weeks.
Two consecutive missed payments.
I immediately opened my personal banking app and pulled up my credit monitoring tool through Experian.
My credit score, which had sat at a pristine 792 in January, had dropped like a stone thrown into a quarry.
**714.**
A seventy-eight-point drop in less than sixty days. Two 30-day late marks reported directly to the credit bureaus under my name.
My throat felt tight, the air suddenly thin and hot in the enclosed garage. Laurel and I were planning to refinance our primary mortgage in July to pull out equity for an addition over the garage. A 714 score meant thousands of dollars in higher interest rates, if we could even qualify with an active derogatory mark on an installment auto loan.
I didn't sleep that night.
I lay on my back in the dark, staring at the textured ceiling plaster, listening to the rhythmic, deep breathing of Laurel beside me. Every time I closed my eyes, I didn't see numbers or credit reports; I saw Beckett on that park bench, holding that stupid little green plastic dinosaur against his ribs, watching the gray smoke drift up from his candle while thirty people screamed for his cousin.
At seven-thirty on Monday morning, I didn't drive to my office in Charlotte.
I drove straight to an office park off Park Road and pulled into the visitors' lot outside a modest two-story brick building with a sign that read: *VANCE & ASSOCIATES — CERTIFIED PUBLIC ACCOUNTANTS & FINANCIAL CONSULTING.*
Wes Vance was already in his office. He had a mug of dark roast coffee in one hand and was scanning a spreadsheet across two oversized monitors. Wes had been my closest friend since our freshman year at NC State. He had been the best man at my wedding; I had been the best man at his. He was a CPA who lived his life by the cold, unforgiving laws of double-entry bookkeeping, and he had zero patience for emotional nonsense.
When he saw me standing in his doorway carrying the yellow legal pad and a manila folder, he didn't ask how I was doing. He just stood up, kicked the door shut behind me, and pointed to the leather armchair across from his desk.
"You look like hell," Wes said bluntly.
"I didn't sleep," I replied, dropping the folder onto his blotter.
"I don't blame you. That circus at the park on Saturday was the most disgusting display of narcissistic garbage I’ve seen since my sister tried to announce her engagement at my grandmother's funeral." Wes sat down and pulled the folder toward him. "I helped the rental crew load up the bounce house, by the way. Your brother didn't lift a finger. He stood by his truck drinking a Corona he snuck out of his cooler while your mom packed the leftover cake into his back seat."
"Wes, look at the Piedmont Federal paperwork," I said. "He’s sixty-two days behind. My credit dropped seventy-eight points."
Wes opened the folder, his analytical eyes scanning the loan documents, the printouts of my bank statements, and the yellow legal pad where I had itemized every single dime over the last three years.
He didn't speak for ten minutes. The only sound in the office was the clicking of his computer mouse and the occasional sip of coffee.
Finally, he leaned back in his high-backed leather chair, folded his hands behind his head, and stared at me through his wire-rimmed glasses.
"Fourteen grand," Wes said quietly. "Olly, you’ve basically been subsidizing his entire existence while he treats you like an ATM that prints out guilt."
"What do I do about the truck?" I asked. "If Piedmont repossesses it, it goes to auction. They sell it for wholesale—probably nine or ten grand—and then they sue both of us for the deficiency balance of eight or nine thousand dollars. It’ll sit on my credit report for seven years like a dead body."
"Can you afford to pay off the arrears right now?"
"Yeah. It’s eight hundred and thirty-six dollars. I have that in checking. But if I pay it, I’m just resetting the clock for him to do it again in June."
Wes tapped his pen against the wooden edge of his desk. "Then we don't just pay it. We sever the legal tie. You co-signed the note, but whose name is on the North Carolina title?"
I blinked. "I... I think both of us. It was supposed to be *Oliver Miller OR Tate Miller.*"
"Find out for certain," Wes said. "Because if it’s *OR*, either party can sell or surrender the vehicle without the other's consent. But if it's *AND*, you're legally tethered to that deadbeat until the note is satisfied."
Wes leaned forward, pulling his keyboard closer. "Now, give me your full Social, your current address, and let’s pull your comprehensive multi-bureau credit report. Not the free consumer summary from your banking app. Let's pull the raw Tri-Merge report through my professional portal. If he’s missed two payments on this truck, I want to see if there's any other collateral damage."
"What do you mean?"
"I mean," Wes said, looking over the top of his glasses with a grim, flat expression, "when people like your brother start drowning, they don't look down to see whose hands they're stepping on to keep their mouths above water."
I sat in the leather chair, watching Wes type my personal information into his secure portal. The soft clatter of the mechanical keys seemed excessively loud in the quiet room.
Wes clicked *SUBMIT.*
A small blue loading wheel spun in the center of his primary monitor. One second. Two seconds. Three seconds.
The screen refreshed with an eighty-page comprehensive credit profile from Equifax, Experian, and TransUnion.
Wes began scrolling through the trade lines. Auto loans, my mortgage, Laurel’s student loans from her master's program, our two credit cards.
Then, about halfway down page twelve, Wes’s hand froze on the mouse.
He stopped scrolling.
His eyebrows pulled together, forming a deep, sharp crease between his eyes. He leaned forward until his nose was barely six inches from the screen.
"Wes?" I asked. The air in my lungs suddenly felt heavy. "What is it?"
Wes didn't answer immediately. He reached out, grabbed a yellow highlighter from his ceramic mug, uncapped it with his teeth, and clicked to print a three-page section of the report. The office laser printer in the corner whined to life, spitting out warm, crisp pages into the tray.
Wes stood up, grabbed the pages, and laid them flat on the desk directly in front of me.
He took the yellow highlighter and drew a thick, violent streak across an account listed under *REVOLVING CREDIT / UNSECURED COMMERCIAL.*
"Tell me you opened a commercial line of credit with SunTrust Bank eighteen months ago," Wes said. His voice was no longer that of a sympathetic friend. It was the voice of a forensic auditor who had just uncovered a crime scene.
I stared at the paper.
**CREDITOR: TRUIST / SUNTRUST COMMERCIAL**
**ACCOUNT TYPE: REVOLVING BUSINESS LINE**
**OPEN DATE: OCTOBER 14, 2022**
**CREDIT LIMIT: $15,000.00**
**CURRENT BALANCE: $14,210.88**
**STATUS: 30 DAYS PAST DUE**
**PRIMARY APPLICANT: OLIVER MILLER (DBA: MILLER CRAFTSMAN SERVICES)**
**MAILING ADDRESS: 412 SYCAMORE STREET, BELMONT, NC**
The room seemed to tilt sideways.
Miller Craftsman Services.
That was Tate’s registered LLC. The one-man drywall and handyman business he had registered with the North Carolina Secretary of State in 2021.
And the mailing address listed on the account was 412 Sycamore Street. Tate’s rental house.
The house whose security deposit I had paid.
"Olly," Wes said, his voice dropping into a low, terrifying whisper. "Did you authorize this?"
"No," I whispered. My throat felt like it was coated in sand. "No. I’ve never had an account with SunTrust in my life. I don't own Miller Craftsman Services. That's Tate's company."
"Look at the Social Security number listed for the primary guarantor," Wes said, pointing his finger at the line.
The first five digits were masked with asterisks.
The last four digits were printed clearly in black ink: **7741.**
My Social Security number.
Not Tate’s.
Mine.
Fourteen thousand two hundred and ten dollars. Drawn against a commercial credit line opened in my name, using my credit profile, routed to his rental house, and now thirty days past due.
May you like
I sat in the leather armchair of my friend's office, staring at that piece of paper, while the world I thought I lived in collapsed into dust.
***